1259
 +66 2039 5704
 Click

My Home Flexi
MSIG My Home Flexi is a flexible home insurance plan that allows you to tailor coverage limits to suit your needs. It provides protection for your home and belongings against fire, lightning, explosion, vehicle impact, aircraft impact, and water damage. You can also choose additional coverage for natural disasters, burglary, and personal liability to third parties. This flexibility enables homeowners to customize their protection according to their lifestyle, level of risk, and budget.
Key features

Coverage for both the building and its contents with sums insured of up to 50 million Baht.

Optional Natural Perils coverage with limits of up to 100,000 Baht.

Optional Burglary coverage with limits of up to 300,00 Baht.

Optional Personal Lliability coverage for third party with limits of up to 2 million Baht.

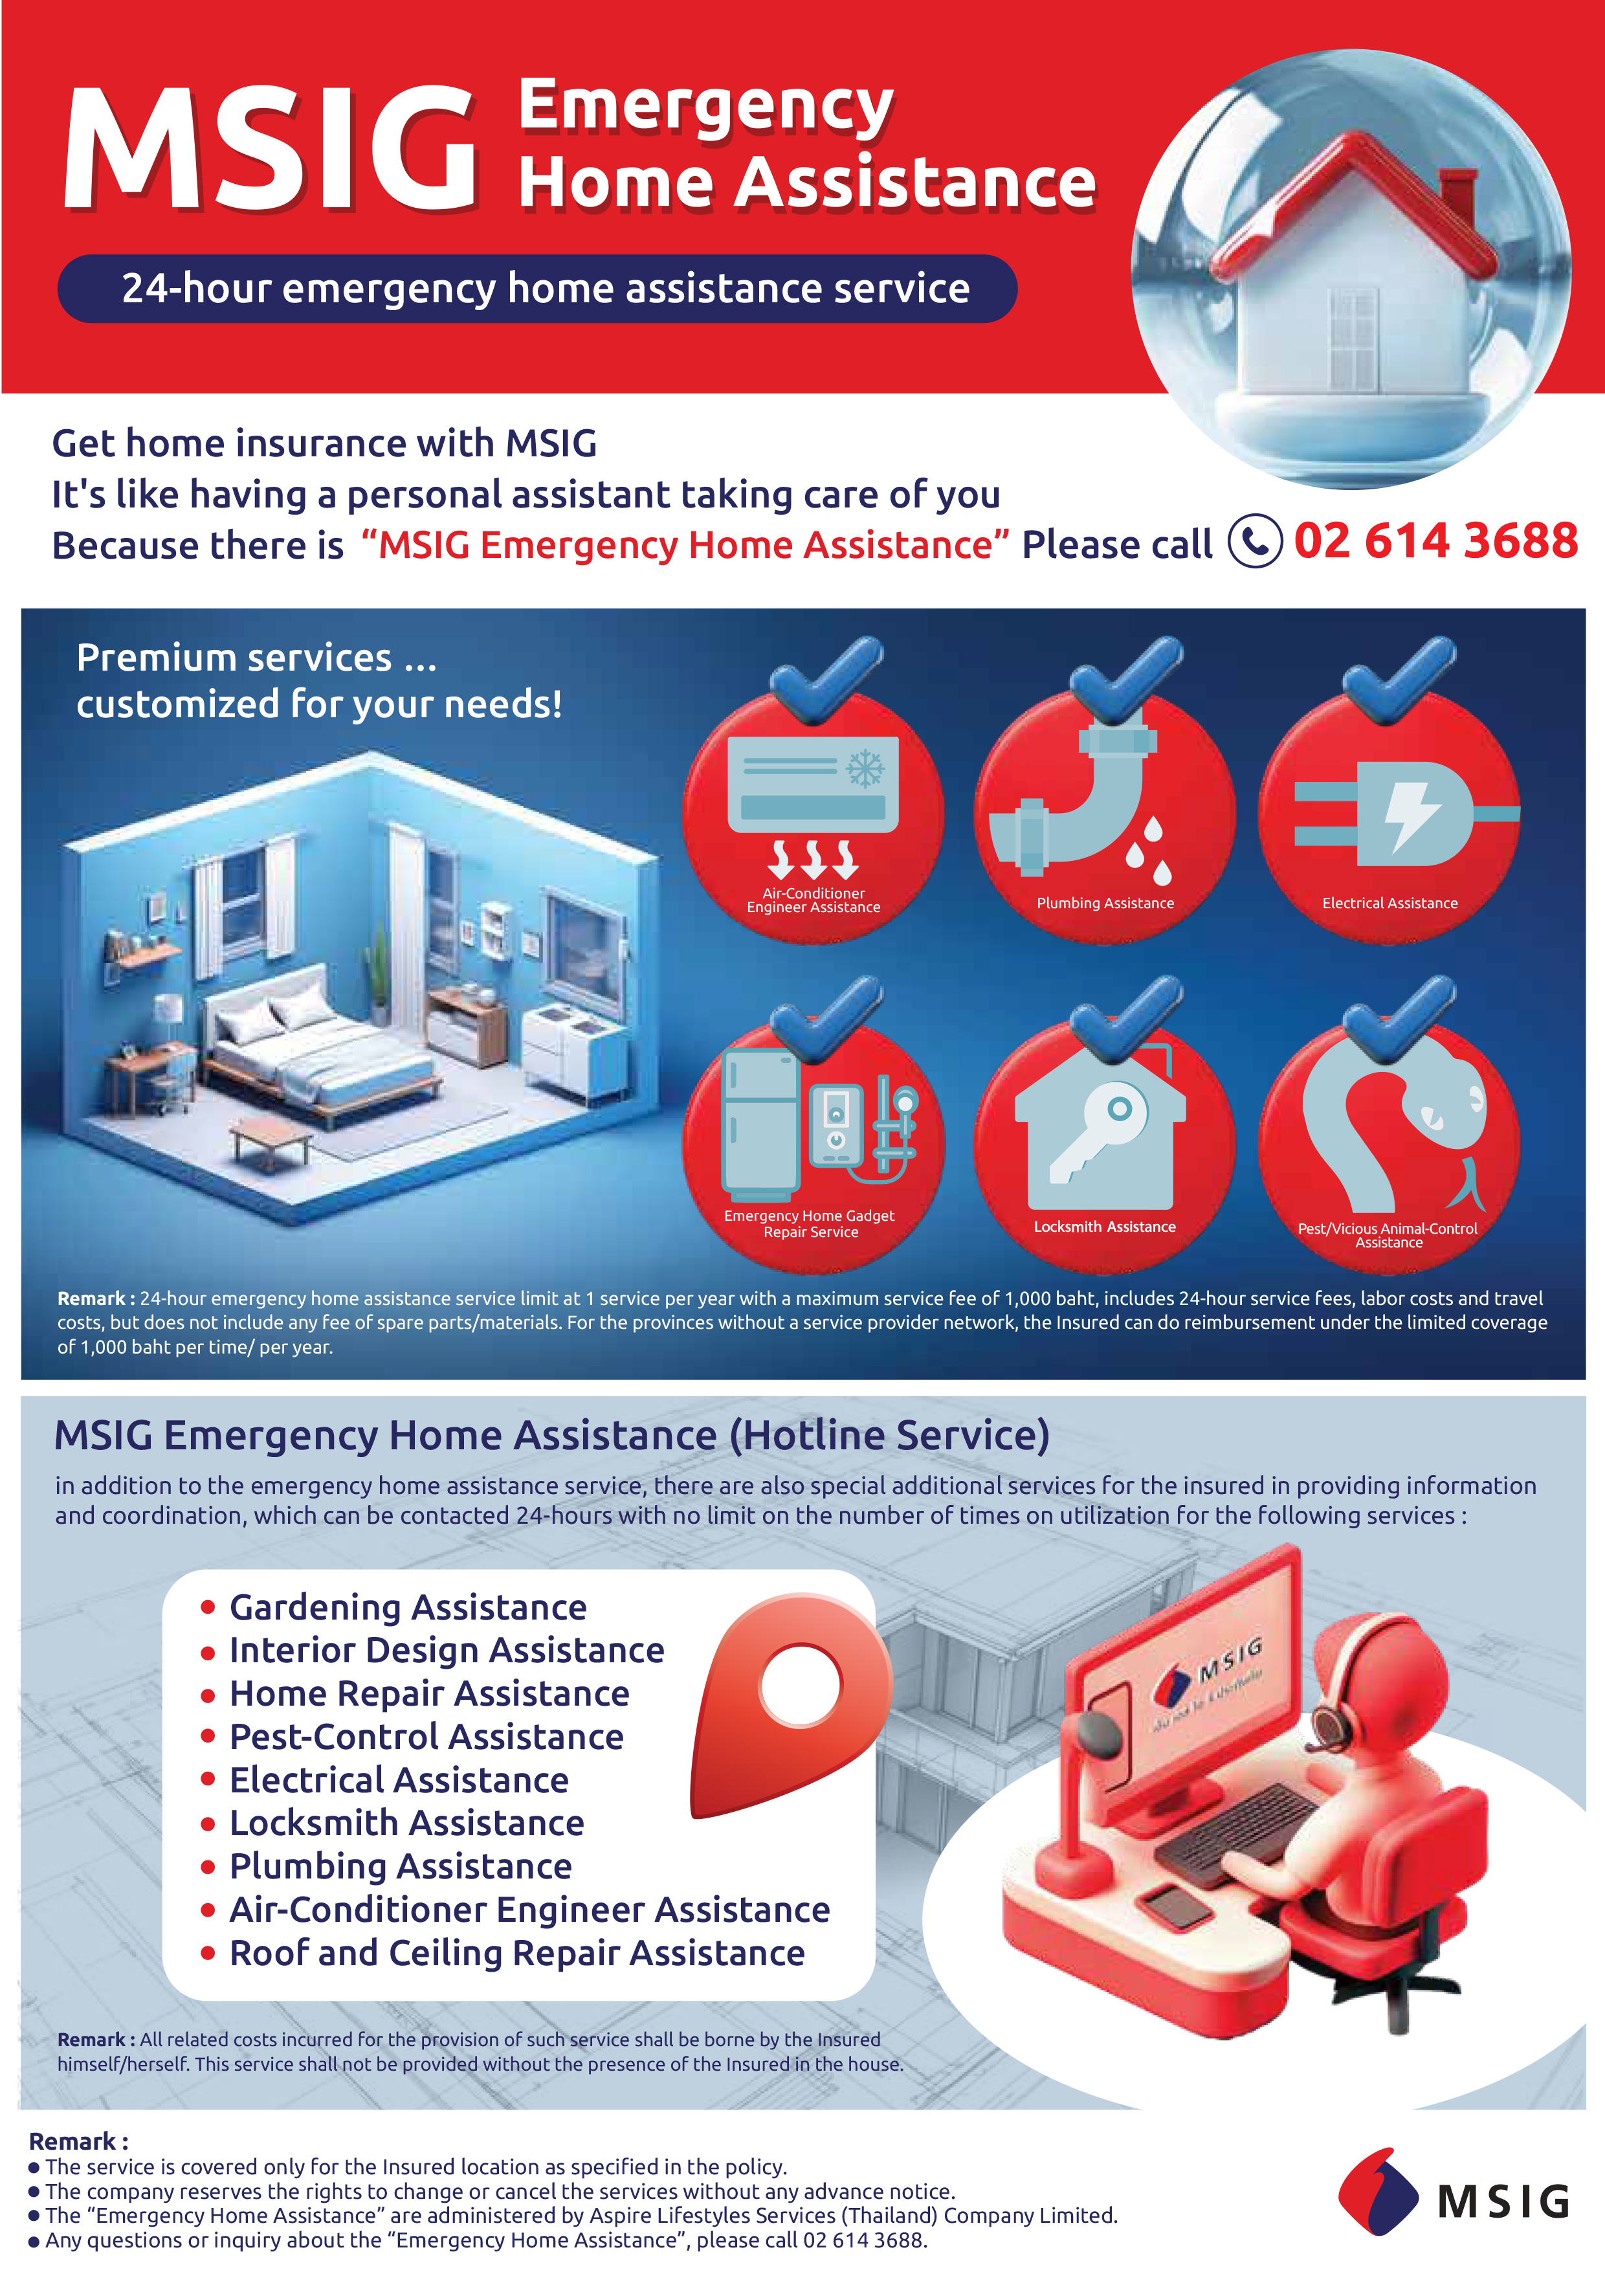
Additional cover for 24-hour Emergency Home Assistance.
Plan details
- Premiums start from 1,986 Baht.
- Provision of rental fee for temporary accommodation in the event amount of loss exceeds 50%.
- Coverage for fire and basic perils affecting the home, up to the sum insured.
- Personal Accident coverage for the insured, up to 200,000 Baht.
- Accidental death coverage for family members or occupants residing in the home, up to 300,000 Baht, arising from covered events.
- Enjoy premium discounts when purchasing a 3-year or 5-year policy.
Coverages | Sum Insured/ Limit of Liability (Baht) per occurrence and per year |
|---|---|
1. Fire |
|
Fire, Lightning (including loss or damage to electrical appliance and equipment caused by short circuit from lightning), Explosion, Vehicle Impact, Aircraft, Smoke, Water Damage (excluding Flood) | Up to Sum Insured |
Natural Perils: Flood, Windstorm, Earthquake or Volcanic Eruption or Tidal wave or Tsunami and Hail | 20,000 |
Additional Perils: | |
Smoke | Up to Sum Insured |
Hail | 200,000 |
Windstorm | 200,000 |
Earthquake, or Volcanic Eruptions, or Tidal Wave/Tsunami | 200,000 |
Flood | Adjustable Coverage Limit |
Strike Riot Malicious Act | 200,000 |
Electrical Injury (arising from Lighting or resulting in fire) | Adjustable Coverage Limit |
Expense and/or Fee for Temporary Accommodation | Covered |
2. Burglary (Theft (with forcible entry to or exit from insured building), Robbery, Gang-Robbery) |
|
Loss/Damage to property insured kept inside building or structure | Adjustable Coverage Limit |
Damage to the building or structure containing the property insured, including its doors or windows, locks and keys | |
3. Plate Glass |
|
Breakage or damage caused by accident of insured plate glass that are fitted or fixed as part of buildings (excluding mirrors, display window glass and show case glass) | 50,000 |
4. Personal Liability |
|
Cover legal liability of the Insured in respect of loss of life, bodily injury, illness or health of Third Party, or loss of or damage to property of Third Party | Adjustable Coverage Limit |
5. Personal Accident |
|
Personal Accident for the Insured, age 1-70 years only : Cover Accidental Death, Dismemberment, or Loss of Sight/ Hearing/ Speech, or Total Permanent Disability (excluding Motorcycle Accident) | 200,000 |
Compensation for Loss of Life of the Members of Insured's family and/or Domestic Servant and/or person who normally reside with the Insured affected upon within the Insured premises and caused by perils under Coverage Section 1 : Fire and Additional Perils or Coverage Section II: Burglary (Bht.100,000 per person, maximum 3 persons, age 1-70 years) | 300,000 |
Additional Extensions for Coverage Section 1 : Fire & Additional Perils |
|
Loss/Damage to Personal Effects | 10,000 per occurrence and 100,000 per year per item |
Fire Extinguishing Expenses | |
Loss/Damage caused by Falling Aerial Antenna and/or Tree | |
Debris Removal Expenses | |
Professional Costs & Fees in respect of Architects, Surveyor, Consultant Engineer, Legal Advisors | |
Awnings, Blinds, Signs, or Other Outdoor Fixtures or Fittings Costs |
Protect Your Home Investment with MSIG Solar Cell Coverage
Installing a solar cell system is a smart way to reduce electricity costs. To further protect your investment, consider securing appropriate insurance coverage for your solar panels and related equipment.
MSIG Home Insurance allows you to extend coverage for your solar cell system by specifying a separate sum insured for the solar cell installation, distinct from the sum insured for your home and other insured property.
Solar cell coverage can be added under the following MSIG home insurance policies:
- Baan Than Rak Insurance
- Exclusive Home Protection Insurance
- Fire Insurance Policy for Dwelling House
MSIG helps protect your home and solar cell system against loss or damage to solar panels and related equipment arising from insured perils such as fire, lightning, flood, windstorm, and natural disasters. By specifying a separate sum insured for the solar cell system, you can ensure that the coverage appropriately reflects its value.
Protect your home and solar cell system with coverage designed to meet your needs.
For more information about solar cell coverage, please contact MSIG or your insurance agent.
📌 Applicable to On-Grid and Hybrid solar cell systems only.
All conditions, coverage, and exclusions are as specified in the insurance policy. The Applicant is advised to study the details of coverage and conditions before deciding to buy insurance. The amount of coverage and benefits depend on the insurance plan.
Premiums will be determined based on the selected limit of liability and sum insured. Please contact MSIG for a quotation.
MSIG Contact Centre
Tel: 02 007 9035
Email: Click here
Monday – Friday (8.30 a.m. – 9.00 p.m.), Saturday (9.00 a.m. – 6.30 p.m.)
(Except Sunday and Official Holidays)
A: My Home Flexi is a customizable home insurance plan that allows you to tailor your coverage to your needs, with flexible options to select coverage limits and add additional protection.
A: It covers houses, residential units, and personal property within the residence from fire, lightning, explosion, water damage, floods, windstorms, earthquakes, hail, electrical Injury, theft, accidental glass breakage, personal liability, and personal accidents.
A: The insurance value of buildings is calculated based on the estimated construction cost, excluding land and foundations.
A: It covers your home and property within your home, and it also covers damage to neighboring houses under the section for personal liability.
A: Yes, the My Home Flexi plan covers the cost of temporary accommodation.
A: If the sum insured is less than 70% of the actual value of the insured property at the time of loss, the insured shall be considered as self-insured for the uninsured portion and must bear the loss proportionately, in accordance with the Average Clause. For example, if a house has an actual value of THB 2,000,000 but is insured for only THB 1,000,000 (equivalent to 50% of its actual value), and a loss of THB 100,000 occurs, the insurance company will compensate only 50% of the loss, or THB 50,000. The remaining amount of THB 50,000 must be borne by the insured. Therefore, to ensure adequate coverage in the event of a loss, the sum insured should be as close as possible to its actual value.
A: Premium discounts are available compared to purchasing an annual policy. The premium for a 3-year policy is 250% of the annual premium, while the premium for a 5-year policy is 349% of the annual premium.
A: You may contact MSIG or your insurance agent to add the Solar Cell system as an insured property item and specify the sum insured for the Solar Cell system separately.
A: The sum insured should reflect the actual value of the Solar Cell system and be declared separately from the sum insured for the home and other insured property.
A: Coverage is available for On-Grid and Hybrid Solar Cell systems. On-Grid: Connected to the public electricity grid. Hybrid: Connected to the public electricity grid and equipped with a battery storage system for backup power.
A: It is recommended to prepare documents related to the Solar Cell installation, such as receipts, quotations, or other relevant documents, to support the underwriting assessment. If such documents are unavailable, for example in the case of a second-hand home purchase, the Company may consider coverage on a case-by-case basis, subject to the applicable underwriting guidelines and conditions.